
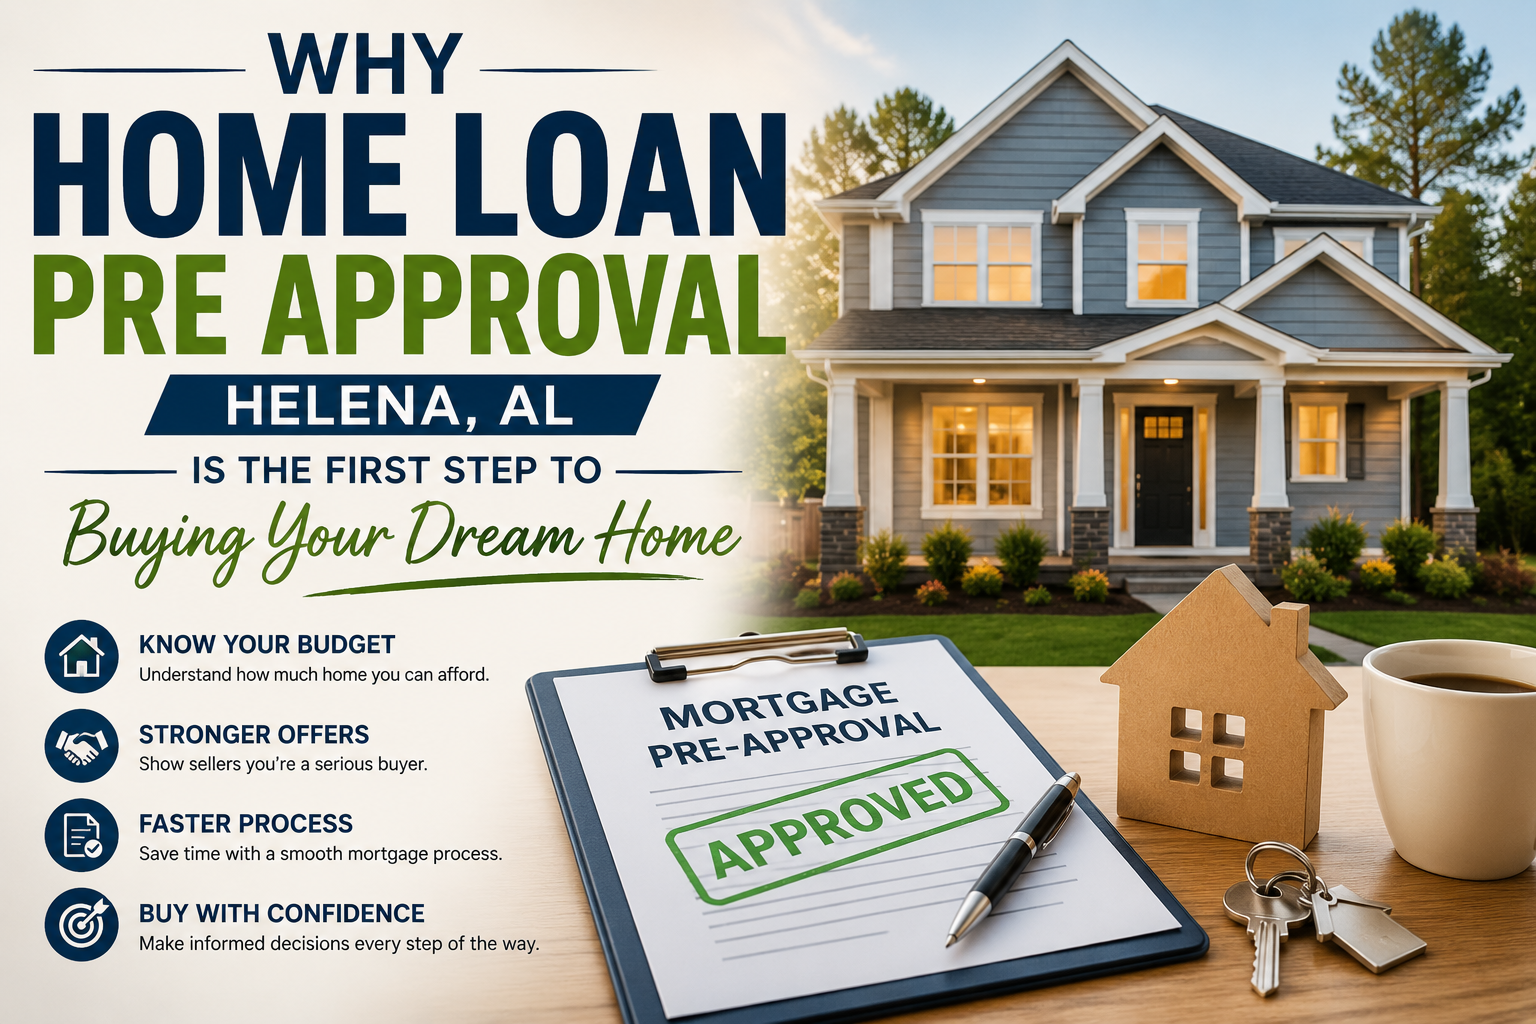
Many people begin the home-buying journey by browsing online listings or driving through neighborhoods they like. While there is nothing wrong with dreaming about a future home, experienced buyers know that one step should come before everything else—getting pre-approved for a mortgage. Understanding the value of Home Loan Pre Approval Helena AL can save time, strengthen your buying position, and make the entire process less stressful.
For first-time buyers especially, pre-approval removes much of the guesswork. Instead of wondering whether a home fits your budget, you have a clearer picture of what you can realistically afford and what lenders may be willing to finance.
What Does Mortgage Pre-Approval Really Mean?
A mortgage pre-approval is an early review of your financial profile by a lender. During this process, information such as your income, employment history, debts, and credit background is evaluated to estimate how much you may qualify to borrow.
Unlike a simple online calculator, pre-approval is based on actual financial details. It gives buyers confidence and helps create a practical home-buying strategy before they start making offers.
Many local buyers begin by speaking with trusted professionals like David Tyson – Steel City Mortgage to better understand the documents and information needed before applying.
Why Pre-Approval Should Come Before House Hunting
Looking at homes without knowing your budget can lead to disappointment. It is easy to become interested in a property that is outside your price range or overlook a home that would actually fit your financial goals.
A Home Loan Pre Approval Helena AL helps by:
- Establishing a realistic home-buying budget.
- Saving time during the search process.
- Giving sellers confidence that you are a qualified buyer.
- Helping identify potential financial issues before they become problems.
- Making the final mortgage process more efficient.
In competitive markets, sellers often prefer offers from buyers who have already completed the pre-approval process because it reduces uncertainty.
The Financial Information Lenders Usually Review
Pre-approval is not about having perfect finances. It is about understanding your overall financial picture and determining whether a mortgage payment fits comfortably within your budget.
Lenders commonly review:
- Current employment and income.
- Existing monthly debts.
- Credit history and payment habits.
- Available savings and assets.
- Debt-to-income ratio.
Having these details organized ahead of time can make the process smoother and reduce delays.
Common Myths About Mortgage Pre-Approval
Many first-time buyers avoid pre-approval because they believe a few common misconceptions.
“I Need a Perfect Credit Score”
A strong credit history is helpful, but several mortgage programs are available for buyers with different financial backgrounds. Lenders often consider the complete picture rather than focusing on one number.
“I Must Save 20% for a Down Payment”
This is one of the biggest myths in home buying. Depending on the loan program, qualified buyers may have access to options with lower down payment requirements.
“Pre-Approval Locks Me Into One Loan”
Getting pre-approved simply gives you an estimate of your borrowing power. It does not force you to purchase a home immediately or prevent you from exploring different loan options.
How Pre-Approval Helps First-Time Buyers
For someone purchasing a home for the first time, there can be a lot of uncertainty. A pre-approval provides direction and allows buyers to focus on properties that match their financial plans.
It also gives you time to fix small issues before the final loan application. If a lender recommends reducing debt or updating financial records, you can address those items before making an offer on a property.
This preparation often creates a smoother experience once you decide to Apply For Home Loan Helena AL and move toward closing.
Documents You May Need
Preparing paperwork before starting the process can make pre-approval much easier. While requirements vary, lenders commonly request:
- Government-issued photo identification.
- Recent pay stubs.
- W-2 forms or tax returns.
- Bank account statements.
- Employment information.
- Details about existing loans or monthly obligations.
Keeping these records organized can speed up both the pre-approval and final mortgage application stages.
Mistakes to Avoid Before and After Pre-Approval
Receiving a pre-approval is an important milestone, but buyers should continue managing their finances carefully until the home purchase is complete.
A few things to avoid include:
- Opening new credit cards.
- Financing a car or large purchase.
- Missing bill payments.
- Making unexplained large bank deposits.
- Changing jobs without discussing it with your lender.
Simple decisions like these can affect the final loan review and create avoidable complications.
More Than a Number on a Piece of Paper
Many people think pre-approval is only about finding out how much money they can borrow. In reality, it is also an opportunity to learn about different mortgage products and understand which option works best for your lifestyle.
Some buyers may discover that a lower monthly payment is more valuable than purchasing the most expensive home they qualify for. Others may realize they can comfortably afford more than expected after reviewing their finances.
A conversation with local mortgage experts, including David Tyson – Steel City Mortgage, can provide helpful insights and allow buyers to make informed decisions before moving forward.
Building Confidence Before Making an Offer
Buying a home is one of the largest financial commitments most people make. Entering the market with a mortgage pre-approval gives buyers greater confidence because they know they have already taken an important step toward financing.
It also makes communication with real estate agents and sellers easier. Instead of starting from scratch after finding a property, much of the early financial review has already been completed.
For first-time buyers, that preparation can turn a stressful experience into a much more organized and enjoyable process.
Conclusion
Every successful home purchase starts with a plan, and mortgage pre-approval is one of the smartest ways to begin. It helps you understand your budget, improves your position with sellers, and gives you time to prepare financially before making one of the biggest investments of your life.
If you are thinking about buying a home, exploring Home Loan Pre Approval Helena AL before you begin house hunting can make the journey much easier. Taking this simple step and working with experienced professionals like David Tyson – Steel City Mortgage allows you to move forward with clarity, confidence, and a better understanding of your home financing options.
Frequently Asked Questions
What is a home loan pre-approval?
A home loan pre-approval is a lender’s preliminary review of your financial information to estimate how much you may qualify to borrow.
Does pre-approval guarantee a mortgage?
No. Pre-approval is an early assessment, while final loan approval depends on additional verification and the property you choose.
How long does a mortgage pre-approval usually last?
Many pre-approvals remain valid for a limited period, although the exact timeframe depends on the lender and your financial circumstances.
Should I get pre-approved before looking at homes?
Yes. Getting pre-approved first helps you understand your budget and can make the home-buying process smoother and more efficient.